
How Tax for Consultants Works Under the FIG Regime: A Simple 2025 Guide

Are you a consultant working in the UK and earning money from abroad? Unsure if you need to pay UK tax on foreign income? You’re not alone; lots of people are wondering the same things in 2025.
The Foreign Income and Gains (FIG) regime is a set of rules for the tax for consultants that may help you avoid paying UK tax on income you earn from outside the country. But it is not automatic — you need to understand who can use it, what income it covers and how to claim it the right way.
It can be helpful, but it also comes with a few things you might lose, like personal tax allowances. So, it is important to weigh the benefits and check if the claim really works in your favour.
Let’s break it down in the simplest way possible, so you can make the right decision with confidence.
Who Qualifies for the FIG Regime?
You need to be a “qualifying new resident” to qualify. That means:
- You were a non-UK resident for at least 10 consecutive tax years before arriving.
- You are not part of the House of Commons or Lords in any year you claim.
Your four FIG years start with the year you arrive in the UK — even if it’s late in the tax year.
Which Types of Income Are Not Taxed Under the New FIG Rules?
If you meet the requirements, you won’t pay UK tax on your foreign income and gains for up to four years. This includes:
- Foreign interest income.
- Dividends from non-UK companies.
- Overseas rental income.
- Distributions from offshore trusts.
- Capital gains on non-UK assets.
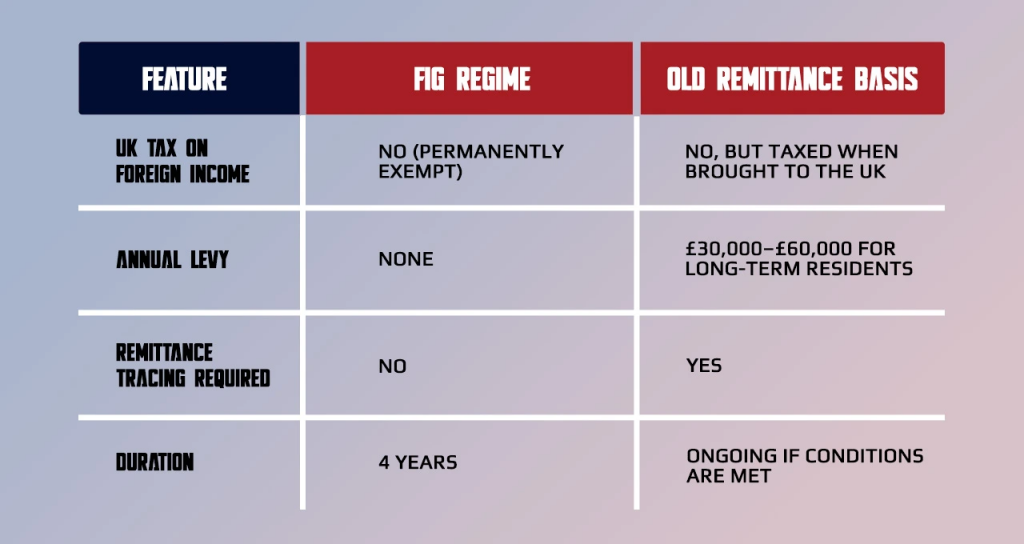
FIG Regime vs Remittance Basis: What’s Changed?
| Feature | FIG Regime | Old Remittance Basis |
| UK Tax on Foreign Income | No (permanently exempt) | No, but taxed when brought to the UK |
| Annual Levy | None | £30,000–£60,000 for long-term residents |
| Remittance Tracing Required | No | Yes |
| Duration | 4 years | Ongoing if conditions are met |
How Can You Claim the FIG Tax Exemption Each Year?’
If you’re living in the UK under the Foreign Income and Gains (FIG) regime, and you qualify, you can enjoy tax-free income from abroad. But to make use of this benefit, you need to officially make a claim. It’s not automatic, and there are a few things you need to do correctly each year. Here’s how:
- Submit your claim by 31 January, two years after the tax year ends (e.g. 31 Jan 2028 for 2025/26).
- Specify each income source (e.g. bank interest, dividends).
- Missed the deadline? You’ll need to rely on HMRC’s late claim policy, which is not guaranteed.
What Do You Lose If You Use the FIG Regime?
While the FIG regime lets you skip paying UK tax on some foreign income, there are a few things you give up when you make the claim. That’s why it is very important to think carefully and speak to a tax expert before deciding.
- You lose your personal tax-free allowance.
- You can’t use your CGT annual exemption.
- Foreign capital losses are not allowed as deductions.
What Happens After the Four FIG Years?
After your FIG window closes, you’ll have to pay UK tax on all your income worldwide. But any income or gains exempted under the FIG regime remain tax-free permanently, even if brought into the UK later.
This gives consultants time to plan their tax affairs, consider pension contributions, or even time a business exit to fall within the FIG period.
Get the Right Tax Help When You Need It Most!
Figuring out the FIG regime on your own can feel confusing, especially when you have to think about deadlines, income types, and what you might lose or gain. That’s where friendly, expert help can make all the difference.
Tax First Consultants will help you every step of the way. Whether you’re new to the FIG regime or just need help filing your claim, our team offers clear advice in simple language — no confusing tax talk.
Reach out to us today and make sure you get the full benefit of your foreign income, without the stress.
FAQs: Tax for Consultants Under the FIG Regime
1. Can I skip a year and still claim later?
Yes, you can. If you don’t use the FIG regime for one year, you can still claim in a later year, as long as it’s within your four-year window.
2. Does the FIG regime cover foreign pensions
Yes, it does. If you are getting a pension from another country, that income counts as part of the FIG regime.
3. What if I only stay in the UK for part of the year?
The FIG regime still applies. The year you arrive in the UK and the year you leave both count towards your four years.
4. Can British citizens returning to Ashford use the FIG regime?
Yes, they can — as long as they have not been UK residents for the last 10 years. So, if you are a British citizen moving back to Ashford after living abroad for a decade, you may still qualify to use the FIG rules.


